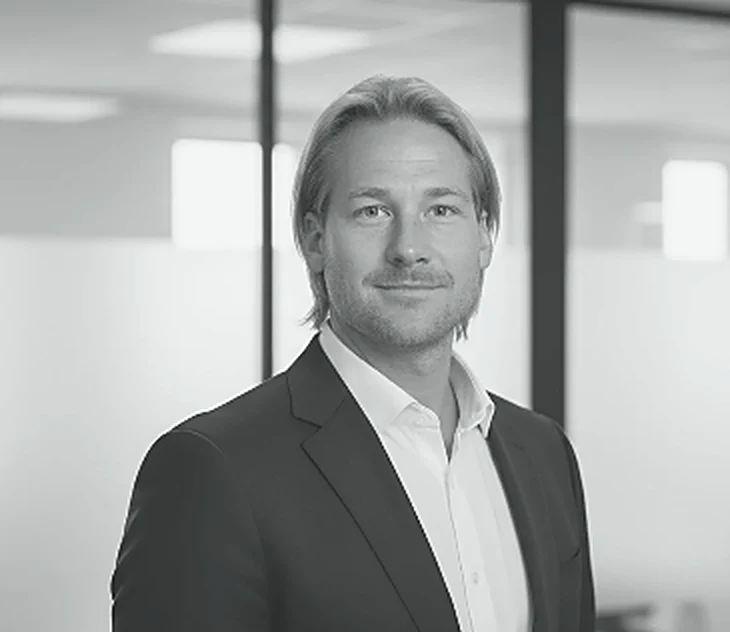
Patrick Wallén
Chairman
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
VoltGuard AB · Org.nr 556601-5490 · Updated 2026-10-06
Strategy
Swedish operating company amounts are converted from SEK at a fixed reference rate of EUR/SEK 11.29. Fund references, international financing references and case studies are shown in original currency where relevant. Conversions are shown for reference only.
Monthly summary
Preparing this month's summary…
AI-generated each month solely from the company's own information on this page. Not reviewed or audited; the company page and legal documents prevail.
VoltGuard is an operating battery-safety product platform: 100 units sold, SEK 3m revenue in 2026 to date, a SEK 5–10m 2026 target and a SEK 100m target for 2027.
From the latest annual accounts in the financials section below.
100 units sold.
SEK 3m to date. Board and company target SEK 5–10m for the full year at a 15–30% profit margin.
“VoltGuard is an operating battery-safety product platform: 100 units sold, SEK 3m revenue in 2026 to date, a SEK 5–10m 2026 target and a SEK 100m target for 2027.”
Role in portfolio: Majority position with the largest relative upside to target.
Every home and commercial battery installation raises a fire-safety question. Insurers, property owners and authorities increasingly require fire-classified enclosures.
Own-developed and produced fire-classified battery cabinets (EI60 described on voltguard.nu), in three variants for residential and commercial use.
100 units sold, SEK 3m revenue in 2026 to date, and distribution through Energy Group's partner network.
The 2027 target of SEK 100m at a 15–30% margin implies SEK 15–30m profit, backed by partner agreements and order tranches. Against a SEK 3m reference value, the re-rating potential is exceptional.
Public accounts show the historical legal-entity position. PVW also reports Board & Management Verified Operating Data where the current commercial reality has moved materially ahead of the latest filed accounts.
100 units sold · SEK 3m in 2026 to date · SEK 100m target 2027
VoltGuard AB (formerly VoltGuard AB) is 51% owned by PVW. Revenue in 2026 to date is SEK 3m; the board and company target SEK 5–10m for full-year 2026 at a 15–30% profit margin. The 2027 target is SEK 100m at the same 15–30% margin. 2027 growth is supported by partner agreements and orders placed in tranches, with sales and distribution through Energy Group’s network and sales channels.
| Revenue to date | €0.27m |
| PVW ownership | 51% |
| Revenue | SEK 5–10m |
| Profit margin | 15–30% |
| Implied profit | SEK 0.75–3m |
| PVW 51% pro-rata | SEK 0.4–1.5m |
| Revenue | €8.86m |
| Profit margin | 15–30% |
| Implied profit | SEK 15–30m |
| PVW 51% pro-rata | SEK 7.7–15.3m |
Pro-rata figures are economic exposure before tax, dividends, rights and financing.
Net sales, operating income, EBITDA, EBIT and net income are never mixed. No figures are interpolated.
| Line item | 2025 (12m) |
|---|---|
| Net sales | €0.0k |
| Net income | −€26.9k |
| Source | Published financial summary |
← Swipe to see the full table →
2025: Product business started after this period; zero 2025 revenue does not mean no current sales.
Legal entity before the product launch.
Three cabinet variants; 100 units sold; SEK 3m revenue to date; SEK 5–10m target at 15–30% margin.
SEK 100m revenue target at 15–30% margin.
Board & Management Verified Operating Data, shown separately from filed accounts.
100 units sold.
SEK 3m to date. Board and company target SEK 5–10m for the full year at a 15–30% profit margin.
SEK 100m target at a 15–30% profit margin, supported by partner agreements and orders placed in tranches.
Sales through Energy Group’s 60+ partner network and channels.
PVW analytical scenario — not company guidance.
| Revenue ↓ / Margin → | 15% | 20% | 25% | 30% |
|---|---|---|---|---|
| €0.44m | €66.4k PVW €33.9k | €88.6k PVW €45.2k | €0.11m PVW €56.5k | €0.13m PVW €67.8k |
| €0.89m | €0.13m PVW €67.8k | €0.18m PVW €90.3k | €0.22m PVW €0.11m | €0.27m PVW €0.14m |
| €4.43m | €0.66m PVW €0.34m | €0.89m PVW €0.45m | €1.11m PVW €0.56m | €1.33m PVW €0.68m |
| €8.86m | €1.33m PVW €0.68m | €1.77m PVW €0.90m | €2.21m PVW €1.13m | €2.66m PVW €1.36m |
← Swipe to see the full table →
Implied profit by the confirmed margin metric; PVW figure is pro-rata exposure before tax, dividends, rights, financing and dilution. Not actual profit, not current valuation, not a guaranteed distribution.
| Multiple of today | 1× | 2× | 3× | 5× | 10× | 20× |
|---|---|---|---|---|---|---|
| Company value | €0.27m | €0.53m | €0.80m | €1.33m | €2.66m | €5.31m |
| PVW attributable | €0.14m | €0.27m | €0.41m | €0.68m | €1.36m | €2.71m |
← Swipe to see the full table →
Illustrative valuation sensitivity — not a forecast or guarantee. Based on equity value, not enterprise value. Growth scenarios are not included in current NAV.
Operating product business: 100 units sold, SEK 3m revenue in 2026 to date.
SEK 100m revenue target in 2027 through partner channels; commercial segment.
Size of residential and commercial battery adoption that drives demand for safe enclosures.
Category reference only. VoltGuard is a safety cabinet, not a battery cell or integrated battery system.
PVW calculations on figures shown elsewhere in this portal (reference values, company budgets, draft accounts, option terms). Simplified and unaudited; targets and budgets are plans, not guarantees.
VoltGuard is carried at a SEK 3m reference — equal to 2026 revenue to date. The Board's 2027 target describes a company of an entirely different size.
The current value prices in almost nothing of the 2027 plan. Even partial delivery would be a step change for PVW's NAV.
PVW internal assessment. Conviction with discipline.
Revenue in place, a partner-backed SEK 100m 2027 target and a reference value that prices in almost none of it.
Data basis: Medium — SEK 3m 2026 revenue to date; 2027 backed by partner agreements and order tranches.
Safety products carry warranty and liability exposure.
Inventory and production scale require financing.
Battery vendors may integrate safety enclosures.
Board and company target at 15–30% margin; SEK 3m to date.
SEK 7.7–15.3m PVW pro-rata profit exposure at 15–30% margin.
SEK 5–10m at 15–30% margin (SEK 3m to date).
Ahead of 2027 tranches.
Released via data room.
Converts partner agreements to revenue.
Funds inventory growth.
Confidential documents are released through the data room on request, never through public links.
Request access: patrickvwallen@gmail.com · +46 70 491 44 43
PVW holds 51% of VoltGuard because battery adoption creates a safety problem that needs a physical product — and VoltGuard is one. PVW contributes board work, distribution via the group network and capital structure. PVW would increase support once distribution agreements and certifications are documented; it would reconsider if unit economics do not hold at scale.
Patrick Wallén · PVW Capital AB · 2026-10-06
The people behind the company
Chairman
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
Source: PVW Capital. Full register details to be added.
A majority position held with board-level involvement alongside the operating team.
PVW ownership: 51%. Controlling ownership. Company value €0.27m, of which €0.14m is attributable to PVW.
Strategy work for owners, boards and management teams — positioning, growth strategy and the structural questions that precede transactions and capital raises.
Advisory demand from owner-led and growth companies that need senior strategic capacity without building it in-house.
A majority position held with board-level involvement alongside the operating team.
Majority ownership enables direction on strategy, governance and use of capital.
Led by its operating partners, with PVW as majority owner represented at board level by Patrick Wallén.
Building a repeatable method and client base, and keeping the business profitable at a modest scale rather than growing headcount for its own sake.
Key person dependency and execution risk.
Beyond its own result, the business gives the group a strategic capability it can apply inside the portfolio — and a natural source of company relationships.