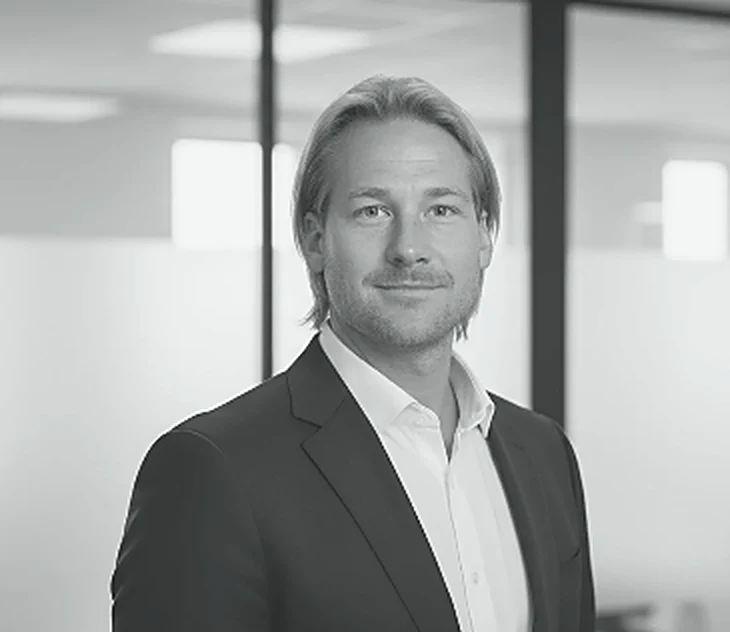
Patrick Wallén
Chairman
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
Elsmarta AB · Org.nr 559466-7379 · Updated 2026-10-06
Energy technology · Energy solutions
Swedish operating company amounts are converted from SEK at a fixed reference rate of EUR/SEK 11.29. Fund references, international financing references and case studies are shown in original currency where relevant. Conversions are shown for reference only.
Monthly summary
Preparing this month's summary…
AI-generated each month solely from the company's own information on this page. Not reviewed or audited; the company page and legal documents prevail.
Elsmarta is transitioning from a small electrical operator into a customer-side energy solutions platform with enterprise relationships, signed work and operational cooperation with VillaKraft, directly owned 30% by PVW Capital AB.
From the latest annual accounts in the financials section below.
SEK 12m expected, supported by agreements and already signed business.
Expected profit margin ~15% — ~SEK 1.8m profit.
“Elsmarta is transitioning from a small electrical operator into a customer-side energy solutions platform with enterprise relationships, signed work and operational cooperation with VillaKraft, directly owned 30% by PVW Capital AB.”
Role in portfolio: Completed 94% PVW Capital AB ownership; controlling operating position with near-term cash generation.
Electrification happens at the customer's site: chargers, batteries, solar, smart control. Whoever owns that customer relationship captures recurring value.
Revenue tripled in 2025 to SEK 5.0m with positive EBITDA. 2026 full-year revenue of SEK 12m at ~15% margin is backed by agreements and signed business.
Operational cooperation with VillaKraft, where PVW directly owns 30%. At its SEK 100m revenue and >30% margin target for 2027, the illustrative pro-rata profit is ~SEK 9m for PVW, not Elsmarta.
Profitable growth and installation volume from cooperation with VillaKraft. The SEK 15m reference value is compared with SEK 1.8m expected 2026 profit; VillaKraft profits belong to its direct shareholders, not Elsmarta.
Public accounts show the historical legal-entity position. PVW also reports Board & Management Verified Operating Data where the current commercial reality has moved materially ahead of the latest filed accounts.
SEK 5.0m → SEK 12m, at ~15% margin
Full-year 2026 revenue of SEK 12m is supported by agreements and already signed business. Siemens and Microsoft relationships are framework / subcontractor relationships for electrical work and energy-related services. Elsmarta cooperates with VillaKraft, where PVW Capital AB directly owns 30%; VillaKraft targets SEK 100m revenue in 2027.
| Sales company revenue target | €8.86m |
| Margin target | >30% |
| Sales company profit | €2.66m |
| PVW 30% direct pro-rata | €0.80m |
Strategic economic exposure — not automatically consolidated revenue. Pro-rata before tax, dividends, rights and accounting treatment.
Pro-rata figures are economic exposure before tax, dividends, rights and financing.
Net sales, operating income, EBITDA, EBIT and net income are never mixed. No figures are interpolated.
| Line item | 2024 (12m) | 2025 (12m) | 2026 (Jan – 12 Nov, prelim.) (10.4m) |
|---|---|---|---|
| Net sales | €0.15m | €0.44m | €0.67m |
| EBITDA | Not disclosed | €18.8k | Not disclosed |
| EBIT | Not disclosed | €17.1k | Not disclosed |
| Profit after financial items | Not disclosed | Not disclosed | €42.2k |
| Net income | Not disclosed | €1.0k | Not disclosed |
| Cash | Not disclosed | Not disclosed | €15.4k |
| Total assets | Not disclosed | Not disclosed | €0.20m |
| Employees | Not disclosed | 4 | Not disclosed |
| EBITDA margin | — | 4.2% | — |
| EBIT margin | — | 3.8% | — |
| Source | Published financial summary | Published financial summary | Board & Management Verified Operating Data |
← Swipe to see the full table →
2025: Growth ~+199.6% (another public summary states ~+194%).
2026 (Jan – 12 Nov, prelim.): Preliminary ledger reports (income statement and balance sheet) printed 12 Nov 2026; year not closed, unaudited. Net sales already +52% vs full-year 2025; profit after financial items SEK 0.48m vs SEK 0.16m in 2025.
Revenue ~SEK 1.7m.
Revenue ~SEK 5.0m, positive EBITDA, 4 employees.
PVW directly owns 30% of VillaKraft; Elsmarta is an operational partner.
Board & Management Verified Operating Data, shown separately from filed accounts.
SEK 12m expected, supported by agreements and already signed business.
Expected profit margin ~15% — ~SEK 1.8m profit.
Siemens and Microsoft: framework / subcontractor relationships for electrical work and energy-related services.
Target SEK 100m revenue and >30% margin in 2027. Management target — not historical result, not forecast guarantee. Strategic economic exposure — not consolidated revenue.
PVW analytical scenario — not company guidance.
VillaKraft is directly held by PVW, not Elsmarta. This is illustrative PVW exposure, not Elsmarta consolidated revenue or booked profit. Subject to consolidation, dividends, tax, minority rights, financing and dilution. Management target 2027: SEK 100m at >30%. Management target — not historical result, not forecast guarantee.
| Multiple of today | 1× | 2× | 3× | 5× | 10× | 20× |
|---|---|---|---|---|---|---|
| Company value | €1.33m | €2.66m | €3.99m | €6.64m | €13.3m | €26.6m |
| PVW attributable | €1.25m | €2.50m | €3.75m | €6.24m | €12.5m | €25.0m |
← Swipe to see the full table →
Illustrative valuation sensitivity — not a forecast or guarantee. Based on equity value, not enterprise value. Growth scenarios are not included in current NAV.
Profitable operator growing to SEK 12m revenue in 2026 on signed business.
Operational cooperation with VillaKraft targeting SEK 100m; enterprise frameworks; recurring service.
Installation and service operating model: scale, project discipline, service mix and margin control.
Operating-model reference only; not a valuation comparable. Exact figures to be taken from Bravida's official annual report.
PVW internal assessment. Conviction with discipline.
Verified operations, near-full ownership and a clear route to standalone scale within the group's energy chain.
Data basis: Medium–high — public 2025 accounts plus signed 2026 business.
Revenue can be lumpy and receivables-heavy.
Small team; delivery depends on few people.
VillaKraft cooperation creates installation opportunities, not a direct profit share for Elsmarta.
Verifies revenue and margin step-up.
Installation opportunities from VillaKraft at target; its profit share belongs directly to PVW.
Backed by signed business.
Puts the step-up into public accounts.
Installation volume from VillaKraft; no Elsmarta equity profit share.
Recurring volume.
Profitable scaling.
Confidential documents are released through the data room on request, never through public links.
Request access: patrickvwallen@gmail.com · +46 70 491 44 43
PVW controls Elsmarta because it is a real, profitable operating business at the customer side of electrification — and because the move into enterprise customers and the cooperation with VillaKraft gives it a second engine. PVW contributes capital discipline, board work and group distribution. PVW would increase support once 2026 figures are filed; it would reconsider if growth comes at the expense of margin.
Patrick Wallén · PVW Capital AB · 2026-10-06
The people behind the company
Chairman
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
Board member
CEO · Deputy board member
Source: Bolagsverket via public company registers (Elsmarta i Sverige AB, 559466-7379).
A controlling position in an energy technology business operating close to the customer side of the energy transition.
PVW ownership: 94%. Controlling ownership. Company value €1.33m, of which €1.25m is attributable to PVW.
Energy solutions delivered close to the end customer — where energy technology meets installation, use and everyday consumption decisions.
The customer-facing part of the Swedish energy transition: households and businesses investing in their own energy solutions as prices, tariffs and grid conditions change.
A controlling position in an energy technology business operating close to the customer side of the energy transition.
Control enables direction on strategy, governance and capital structure.
Run by its own operating team, with PVW represented at board level through Patrick Wallén as controlling owner.
Priorities are a clear commercial offer, disciplined unit economics, and coordination with the other energy holdings in the group where it creates real advantage.
Execution risk and financing requirements in a developing market.
The opportunity is to own the customer relationship in a market that is shifting from one-off installations to ongoing energy optimisation and service.