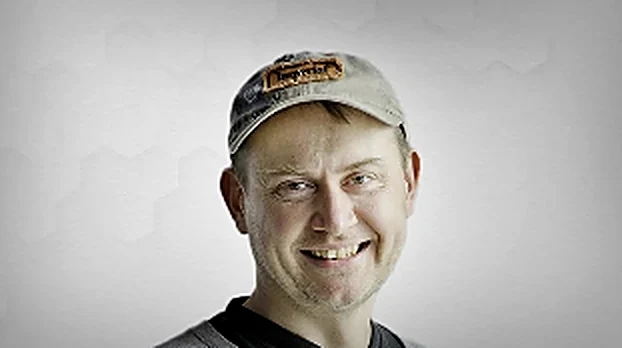
Jonas “Birger” Birgersson
Founder & vice chairman
Swedish entrepreneur, born 1971, who founded Framtidsfabriken (CEO) and Svenska Bredbandsbolaget (chairman) — both billion-dollar companies before he turned 30.
EnergyNet · Updated 2026-10-06
Energy sharing infrastructure · Protocol
Swedish operating company amounts are converted from SEK at a fixed reference rate of EUR/SEK 11.29. Fund references, international financing references and case studies are shown in original currency where relevant. Conversions are shown for reference only.
Monthly summary
Preparing this month's summary…
AI-generated each month solely from the company's own information on this page. Not reviewed or audited; the company page and legal documents prevail.
Increases exposure to local grid infrastructure and energy-sharing protocols ahead of a stated 3–5 year IPO ambition.
Illustrative embedded value gap versus current PVW reference valuations: +€0.66m (discount 42.9% vs reference €31.0m).
The illustrative value gaps are calculated against PVW’s current reference valuations. They become economically relevant only if the relevant option or ownership transaction is completed and the reference valuations remain valid.
All purchase options are conditional on the founders contributing the full exercise proceeds to the company as an unconditional shareholder contribution. The capital is used in the business — not as any form of exit for the founders — and solely to strengthen the company's ability to reach its goals.
An energy-sharing and local-grid infrastructure platform currently operated within the ViaEuropa structure, with a dedicated company planned for 2027.
Paying customers engaged and moving toward large orders.
~USD 285m connected to two projects; USD 5–10m connected to the US expansion.
“An energy-sharing and local-grid infrastructure platform currently operated within the ViaEuropa structure, with a dedicated company planned for 2027.”
Role in portfolio: Highest-valued holding; protocol-level optionality with a signed option to increase.
Grid capacity is the binding constraint on electrification. Sharing locally produced and stored energy inside communities unlocks capacity without waiting for new transmission.
Paying customers, customers moving toward large orders, ~USD 285m in project financing references and a public municipal anchor in CoAction Lund.
An acquisition approach around SEK 250m was rejected; IPO ambition within ~3–5 years; dedicated company formation in 2027.
Becoming the standard coordination layer across housing associations, municipalities and international projects, with recurring platform revenue.
Public accounts show the historical legal-entity position. PVW also reports Board & Management Verified Operating Data where the current commercial reality has moved materially ahead of the latest filed accounts.
Paying customers, large orders in motion, dedicated company 2027
EnergyNet is currently housed within the ViaEuropa / bi-firma structure, where the technology sits. Paying customers are already engaged and moving toward large orders. EnergyNet / ViaEuropa has financing initiatives with customers visible on its website, including references of approximately USD 285m connected to two projects and USD 5–10m connected to the US expansion. A dedicated EnergyNet company is planned for 2027 as the concept scales.
EnergyNet is not yet best understood through a standalone public annual report. The economic value sits in the technology, customer demand, the local-grid infrastructure model, financing structures and the future EnergyNet company formation. PVW's option secures a larger position at a SEK 200m basis ahead of that formation.
Paying customers engaged; customers moving toward large orders; financing initiatives with customers including ~USD 285m across two projects and USD 5–10m for the US expansion (figures as quoted in USD).
Converted reference: ~SEK 3.0B / ~€265M at USD/SEK 10.50.
Municipal energy-community initiative.
PVW invested SEK 650k at a SEK 100m valuation.
Approx. SEK 250m, management-reported.
Signed option on further 5% A-shares at SEK 200m basis.
Board & Management Verified Operating Data, shown separately from filed accounts.
Paying customers engaged and moving toward large orders.
~USD 285m connected to two projects; USD 5–10m connected to the US expansion.
HSB, Riksbyggen and broad municipal relationships.
Around SEK 250m, rejected.
Publicly documented municipal initiative.
~3–5 years. An ambition, not a decided exit.
PVW analytical scenario — not company guidance.
Revenue engines: licences, installation and hardware, project development, operations and service, and recurring network / platform services — scaled through paying customers, large orders and customer project financing. A full earnings model follows the 2027 company formation.
| Multiple of today | 1× | 2× | 3× | 5× | 10× | 20× |
|---|---|---|---|---|---|---|
| Company value | €31.0m | €62.0m | €93.0m | €155m | €310m | €620m |
| PVW attributable | €0.31m | €0.62m | €0.93m | €1.55m | €3.10m | €6.20m |
← Swipe to see the full table →
Illustrative valuation sensitivity — not a forecast or guarantee. Based on equity value, not enterprise value. Growth scenarios are not included in current NAV.
Paying customers, financing initiatives and a rejected ~SEK 250m approach.
Dedicated company 2027; standard-setting local-grid layer; IPO path.
No meaningful comparable has been verified yet; none is shown rather than an unsourced one.
PVW calculations on figures shown elsewhere in this portal (reference values, company budgets, draft accounts, option terms). Simplified and unaudited; targets and budgets are plans, not guarantees.
EnergyNet has already been re-rated from PVW's SEK 100m entry to a SEK 350m reference. The option allows PVW to add 5% at a basis below today's reference.
A position that has already proven its value movement, with a route to six times the current ownership.
PVW internal assessment. Conviction with discipline.
Already re-rated 3.5x since PVW's entry, signed 2026 business and an option to grow the stake sixfold.
Data basis: Medium — operating data verified; standalone accounts follow 2027 company formation.
Local network and energy-sharing rules can change.
Pilots may not convert to paying deployments.
Reference value exceeds the last reported approach.
+5% A-shares at SEK 200m basis.
Paying installations and recurring fees.
+5% A-shares at SEK 200m basis.
Standalone structure as the concept scales.
Recurring platform revenue.
~USD 285m references; US expansion.
Liquidity event.
Confidential documents are released through the data room on request, never through public links.
Request access: patrickvwallen@gmail.com · +46 70 491 44 43
PVW owns EnergyNet because the coordination layer for local energy may become as foundational as the networks it runs on. PVW's direct stake is small; the signed option to add 5% A-shares at a SEK 200m basis is how PVW intends to make it matter. PVW would exercise on documented commercial traction; it would reconsider if regulation blocks commercial energy sharing.
Patrick Wallén · PVW Capital AB · 2026-10-06
The people behind the company
Founder & vice chairman
Swedish entrepreneur, born 1971, who founded Framtidsfabriken (CEO) and Svenska Bredbandsbolaget (chairman) — both billion-dollar companies before he turned 30.
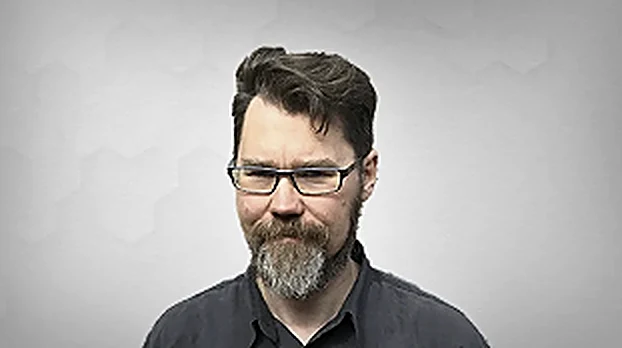
Chief Executive Officer
20-year industry veteran; senior roles at Framfab, co-founder and CEO of Bredband2 when it became the leading independent ISP.
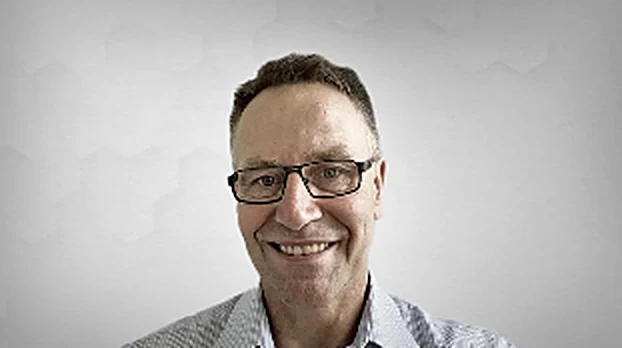
Chief Financial Officer
Background in banking; CFO of the municipal energy company in Växjö from 2000, later turned its broadband network to profitability over 15 years in the energy group.
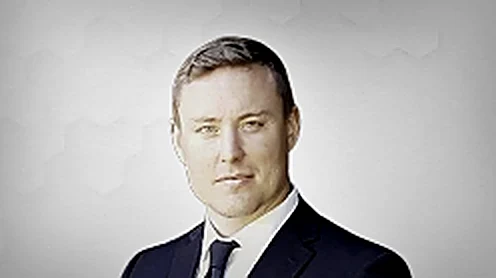
Chief Operating Officer
Twelve years as a command-and-control officer in the Swedish Armed Forces; joined ViaEuropa in 2019 and became COO in 2023.
Senior advisor
Two decades in communication technology: Norwegian Army, ElTele, Formus, CTO at Portit and CTO/COO at Labs² Group 2006–2022.
Board member & advisor
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
Source: viaeuropa.net. EnergyNet is currently owned and operated by ViaEuropa Sverige AB; these are ViaEuropa's management.
EnergyNet aims to provide infrastructure and protocol functionality for energy sharing — conceptually comparable to how communication protocols enabled the Internet. This is an investment thesis, not a guaranteed outcome.
PVW ownership: 1%. Early stage · Strategic position. Company value €31.0m, of which €0.31m is attributable to PVW. PVW invested €57,573 at a €8.86m company valuation.
A new company associated with ViaEuropa and Jonas Birgersson, built around an energy sharing protocol.
Distributed energy and the coordination layer between producers, consumers and the grid.
EnergyNet aims to provide infrastructure and protocol functionality for energy sharing — conceptually comparable to how communication protocols enabled the Internet. This is an investment thesis, not a guaranteed outcome.
A small position taken early, held for optionality rather than influence. PVW contributes through its network in Swedish energy and by staying close to the people building the company.
Associated with ViaEuropa and Jonas Birgersson.
The relevant milestones are technical: a working protocol, first deployments with real energy flows, and partners willing to build on top of it. None of these are guaranteed.
Early-stage risk, adoption risk, regulatory risk and valuation uncertainty. Outcomes are inherently uncertain.
If a shared protocol layer for energy becomes established, the value sits in the standard rather than in any single installation. That is the reason for holding the position — and the reason it is sized as a small one.