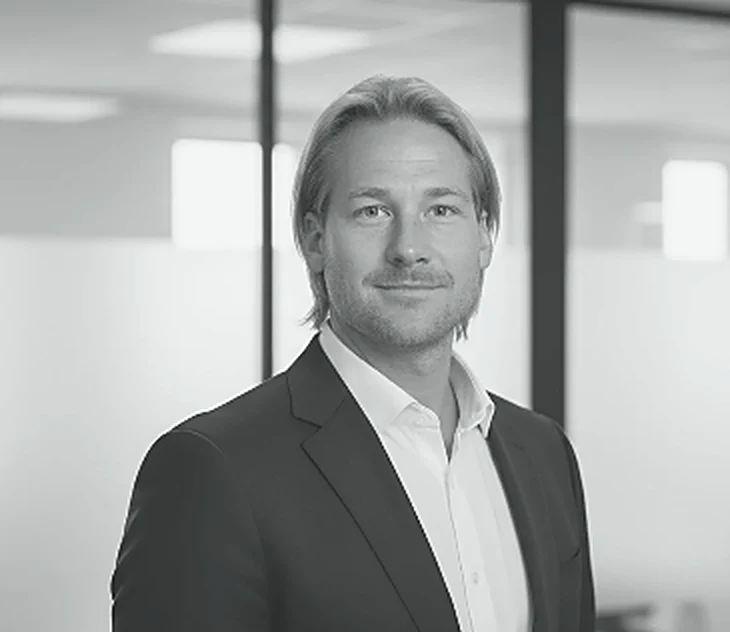
Patrick Wallén
Board member · CEO
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
Kapitalanalyser i Sverige AB · Org.nr 559269-0084 · Updated 2026-10-06
Financial analysis · Investment advisory
Swedish operating company amounts are converted from SEK at a fixed reference rate of EUR/SEK 11.29. Fund references, international financing references and case studies are shown in original currency where relevant. Conversions are shown for reference only.
Monthly summary
Preparing this month's summary…
AI-generated each month solely from the company's own information on this page. Not reviewed or audited; the company page and legal documents prevail.
Kapitalanalyser is entering a 2027 expansion phase: a platform built over several years, now scaling with new customers, larger mandates, new hires with their own customer books and new technology.
From the latest annual accounts in the financials section below.
New customers coming in; existing customers expected to bring larger capital volumes.
New hires coming in with their own large customer books.
“Kapitalanalyser is entering a 2027 expansion phase: a platform built over several years, now scaling with new customers, larger mandates, new hires with their own customer books and new technology.”
Role in portfolio: Wholly owned operating base and analytical engine of the group.
Analysis and structuring capability sources and evaluates every PVW investment — and the same capability is now being sold at scale externally.
2027 commercial target: SEK 5–10m revenue at a 30–40% EBITDA margin, driven by new customers, larger mandates, new hires with their own books, new website, technology and portfolios.
Analysis, education and corporate advisory are kept separate from regulated advice.
Public accounts show the historical legal-entity position. PVW also reports Board & Management Verified Operating Data where the current commercial reality has moved materially ahead of the latest filed accounts.
2027 expansion: SEK 5–10m at 30–40% EBITDA
Historical legal-entity accounts were small. The platform, customer base, technology, portfolio infrastructure and hiring base are now positioned for significant 2027 expansion: new customers are coming in, existing customers are expected to bring larger capital volumes, a new website, new technologies and new portfolios are launching, and new hires arrive with their own large customer books.
Net sales, operating income, EBITDA, EBIT and net income are never mixed. No figures are interpolated.
| Line item | 2023 (12m) | 2024 (12m) |
|---|---|---|
| Net sales | €74.8k | €71.1k |
| Net income | €19.7k | −€2.7k |
| Source | Published financial summary | Published financial summary |
← Swipe to see the full table →
Historical accounts reflect the build phase of the legal entity, not the 2027 platform.
Analysis and advisory activity.
Revenue ~SEK 0.85m, result ~SEK +0.22m.
Build-out toward SEK 5–10m.
Board & Management Verified Operating Data, shown separately from filed accounts.
New customers coming in; existing customers expected to bring larger capital volumes.
New hires coming in with their own large customer books.
New website, new technologies and new portfolios.
SEK 5–10m at 30–40% EBITDA margin.
More than 10,000 unique visitors per month since launch in Q3 2026 (company-reported).
Patrick Wallén is a board member and will become chair once the new hires and a new CEO are in place.
PVW analytical scenario — not company guidance.
| Revenue ↓ / Margin → | 30% | 35% | 40% |
|---|---|---|---|
| €0.44m | €0.13m PVW €0.13m | €0.16m PVW €0.16m | €0.18m PVW €0.18m |
| €0.66m | €0.20m PVW €0.20m | €0.23m PVW €0.23m | €0.27m PVW €0.27m |
| €0.89m | €0.27m PVW €0.27m | €0.31m PVW €0.31m | €0.35m PVW €0.35m |
← Swipe to see the full table →
Implied profit by the confirmed margin metric; PVW figure is pro-rata exposure before tax, dividends, rights, financing and dilution. Not actual profit, not current valuation, not a guaranteed distribution.
| Multiple of today | 1× | 2× | 3× | 5× | 10× | 20× |
|---|---|---|---|---|---|---|
| Company value | €0.35m | €0.71m | €1.06m | €1.77m | €3.54m | €7.09m |
| PVW attributable | €0.35m | €0.71m | €1.06m | €1.77m | €3.54m | €7.09m |
← Swipe to see the full table →
Illustrative valuation sensitivity — not a forecast or guarantee. Based on equity value, not enterprise value. Growth scenarios are not included in current NAV.
Small, wholly owned advisory business; SEK 4m reference value.
Scalable analysis and wealth-architecture platform.
No meaningful comparable has been verified yet; none is shown rather than an unsourced one.
PVW internal assessment. Conviction with discipline.
Established business with a defined expansion target.
Data basis: Medium — modest history; 2027 expansion set as Board & Management target.
Dependent on the founder until hires are productive.
Must stay within non-licensed scope or obtain permissions.
Revenue per employee becomes measurable.
Revenue capacity.
Customer acquisition.
Larger capital volumes per customer.
30–40% EBITDA.
Revenue quality.
Confidential documents are released through the data room on request, never through public links.
Request access: patrickvwallen@gmail.com · +46 70 491 44 43
Kapitalanalyser is where PVW's analytical method lives. PVW owns it outright because the capability is core to the group. Historical numbers are small and are shown as they are. PVW would invest further when hires prove productive; it would reconsider the stand-alone ambition if external revenue does not follow.
Patrick Wallén · PVW Capital AB · 2026-10-06
The people behind the company
Board member · CEO
Patrick brings over 20 years of experience in finance and capital structuring, ensuring that projects meet institutional requirements and are positioned for scalable investment.
Deputy board member
Source: Bolagsverket via public company registers (Kapitalanalyser i Sverige AB). Patrick Wallén is to become chairman once new hires and a new CEO are in place.
A wholly owned operating business within financial analysis and investment advisory, and one of the core operating businesses of the group.
PVW ownership: 100%. Wholly owned. Company value €0.35m, of which €0.35m is attributable to PVW.
Financial analysis and investment advisory. PVW is the sole owner.
Swedish capital markets and the advisory layer around private and growth companies. Demand follows transaction activity, financing needs and the growing requirement for independent analysis.
A wholly owned operating business within financial analysis and investment advisory, and one of the core operating businesses of the group.
Full ownership allows direct investment decisions and close operational alignment.
Operationally close to PVW. Patrick Wallén is directly involved as owner and board representative; the business is run by its own team within a defined mandate.
The focus is a more recurring revenue base, a repeatable analysis and advisory methodology, and closer integration with the rest of the group as an analytical resource.
Key-person dependency and regulatory risk inherent in advisory activity.
As a wholly owned business it can carry group-level analysis capacity, generate cash for reinvestment, and scale through productised analysis rather than purely through hours sold.